

myWisely: Mobile Banking

- 12.12K Reviews
- 4.3
- Downloads
- 5,000,000+
Our take on myWisely: Mobile Banking from Appgk
I see myWisely: Mobile Banking as a practical money-management app for people whose pay and everyday spending already fit the Wisely ecosystem. Its central appeal is simple: it brings pay access, spending oversight, and saving habits into one mobile place instead of making you move between a payroll portal, a separate budgeting app, and a traditional bank dashboard. That focus makes it useful, but it also defines its limits. This is not the app I would choose as a complete replacement for every kind of bank account.
Developed by ADP, INC., this free finance app is aimed at an Everyone audience and runs on Android starting with version 10. It has been available since April 30, 2019, and the current version is 26.6.0. Its public reception is strong, with a 4.3 average from around 31 thousand ratings, roughly 12 thousand written reviews, and more than 5 million installs. Those figures suggest that it has reached a sizeable audience, but I would still judge it by how well it fits a person’s actual pay and spending routine rather than by popularity alone.
Where myWisely is most useful in daily money management
A focused home for pay and spending
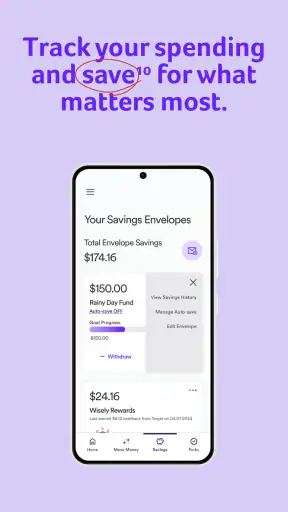
The first strength is concentration. The app is built around the everyday questions people ask after payday: Has my money arrived? How much can I safely spend? Am I putting anything aside? Instead of treating those as separate tasks, myWisely presents them as connected parts of the same routine. I find that more useful than a traditional banking app that may show a balance clearly but leaves budgeting almost entirely up to the user.
That focus is especially helpful for someone who receives pay through a Wisely-related arrangement and wants to check money from a phone. A quick balance check before buying groceries, reviewing recent spending after a weekend, or checking whether enough remains for a bill all become natural uses. The app’s short store message, “Get paid. Track spend. Save more,” describes the intended flow accurately without needing a complicated financial vocabulary.
Best Parts of myWisely: Mobile Banking
Things to Keep in Mind About myWisely: Mobile Banking
I also like the psychological advantage of seeing spending and saving in the same place. Many people know they should save, but the action gets postponed because it feels disconnected from their normal spending. When saving appears alongside pay and purchases, it becomes easier to make a small transfer or set a personal rule immediately after checking available money. The app is most convincing when used as a frequent checkpoint rather than opened only when something has gone wrong.
A realistic payday routine
Imagine a worker being paid near the end of the week. On payday, I would open the app to confirm the incoming money, review what has already been spent, and decide how much can remain available for transport, food, and bills. Before the next payday, I would check the same screen before making a nonessential purchase. That routine does not require a spreadsheet or a separate budgeting service; it simply turns short mobile checks into a basic spending discipline.
News and Features Related to myWisely: Mobile Banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The important detail is timing. Checking after a purchase is more useful than checking only at the start of the month, because the balance reflects decisions that have actually happened. I would also use the app before moving money into savings, leaving a buffer for scheduled expenses instead of treating the visible balance as completely free to spend. That habit is a meaningful strength: the app can encourage better decisions without requiring the user to become a finance enthusiast.
Why the mobile format matters
For this kind of service, mobile access is not just a smaller version of a website. Money decisions happen in shops, at work, on public transport, and between other tasks. A phone-based account view is therefore more relevant than a desktop-only dashboard. I found the concept strongest for quick checks that take seconds, particularly when the alternative is guessing from memory.
Don't want to read the full review?
At the same time, I would not expect a mobile banking app to replace careful financial planning. A small screen is convenient for checking a balance and reviewing recent activity, but less comfortable for studying a long spending history or building a detailed household budget. Users who want category-by-category analysis, extensive charts, or complex account planning may prefer a dedicated budgeting tool alongside myWisely.
Useful insight: separate “available” from “safe to spend”
One of the most important lessons I take from using an app like this is that the displayed balance should not automatically become a shopping limit. Money may already have a purpose, even when it is visible. I would mentally divide the balance into immediate spending, upcoming obligations, and savings before making decisions. That simple three-part check turns a basic account view into a more reliable personal system.
Screenshots
This is also where the app’s simplicity can work in the user’s favor. It does not force a complicated financial method on someone who only needs a repeatable routine. A user can open it, look at the current position, and apply a personal buffer. The trade-off is that the app cannot make those judgments for you; the discipline still belongs to the person using it.
Useful insight: review spending at two different moments
I recommend checking activity twice for different reasons. A quick review soon after payday helps establish a starting point, while a second review before the next pay cycle shows whether small purchases have quietly changed the plan. These checks answer different questions. The first asks, “What do I have to work with?” The second asks, “What did my actual behavior do to that amount?”
That approach is more realistic than expecting one monthly budgeting session to capture every decision. It also helps identify recurring habits, such as frequent convenience purchases or spending that rises on particular days. Even without turning the app into a detailed accounting system, repeated short reviews can make the spending side of the service genuinely useful.
Saving works best when it has a purpose
The saving side is most effective when I attach it to a clear goal rather than treating it as an abstract promise. A user might decide that a portion of incoming pay is for an upcoming expense, an emergency cushion, or a planned purchase. The exact goal is personal, but the workflow matters: check incoming money, protect necessary spending, then move an intentional amount toward saving.
I would avoid transferring so much that the next week becomes difficult. A saving action that causes repeated shortfalls is not a successful habit. The app can make saving more visible, but it cannot determine the right amount for every household. That is a useful distinction for new users who may expect an automated solution to solve irregular income or unpredictable bills.
Where it compares well with ordinary alternatives
Compared with a standard bank app, myWisely feels more purpose-built for the connection between receiving pay and managing day-to-day spending. Traditional bank apps often provide broader account services, but their budgeting tools can feel secondary. Here, the pay-and-spend relationship is the reason to open the app, which makes it easier to build a routine around those actions.
Compared with a standalone budgeting app, the advantage is convenience. A separate budget tracker may offer richer categories, reports, and long-term planning, but it can require manual entry or extra setup. myWisely is a better fit for quick awareness when the user values immediacy over detailed analysis. I would use the two together if I needed both: myWisely for current pay and spending checks, and a more elaborate tool for household planning.
Compared with a full-service bank account, the decision depends on what the user needs beyond everyday money control. Someone looking for a broad financial relationship, multiple account types, extensive planning, or a more traditional banking experience may find another provider more suitable. myWisely’s strength is not trying to be everything; its strength is keeping its main tasks close together.
The meaningful weakness: simplicity has a ceiling
My main reservation is that a focused app can feel limited once a person’s finances become more complicated. If you manage several accounts, split bills with other people, track irregular freelance income, or need detailed historical analysis, a simple pay-and-spend view may not be enough. The app can support a daily routine, but it should not be mistaken for a complete financial planning platform.
There is also a learning curve around expectations. A new user may assume that seeing a balance means every dollar is available, or that a saving feature automatically creates a sensible plan. In practice, the app still depends on the user understanding upcoming obligations and checking activity regularly. I consider that a manageable weakness, but it is important because financial apps can create false confidence when their screens look simple.
Another limitation is fit. If your employer, pay arrangement, or normal banking habits do not connect naturally with Wisely, the app may offer less value than its feature set suggests. I would not download it merely because I wanted a generic budget tracker. Its usefulness comes from the relationship between the service and the way you receive and use money.
What I would check before relying on it
Before making it the center of my routine, I would confirm that my existing pay setup works with the service and that the account presentation matches how I organize money. I would also spend a few days checking activity at different times rather than assuming the first screen tells the whole story. That gives a better sense of whether the app fits real behavior, especially for people with irregular expenses.
I would keep an independent record of important bills during the adjustment period. This is not because the app is unsuitable, but because changing money routines deserves a safety net. Once I knew how the app fit my pay cycle, I could use it more confidently for routine checks and saving decisions.
Who should choose it
I think myWisely is a strong match for people who want a straightforward mobile way to connect pay, spending, and saving. It suits users who prefer short, frequent checks over complicated financial dashboards, and it can be particularly helpful for anyone trying to stop relying on memory between paydays. The free price also lowers the barrier to trying that routine.
It is a sensible option for a person who wants to become more deliberate with everyday money without learning a full budgeting system. Someone who regularly asks, “Where did my pay go?” may benefit from having spending visibility close to the place where pay is managed. The app can also suit users who want to start saving in small, purposeful steps rather than making an ambitious plan they will abandon.
Who should skip it
I would look elsewhere if I needed sophisticated investment tracking, detailed household budgeting, extensive account aggregation, or a complete replacement for a broad banking relationship. A dedicated budget application may be better for category analysis, while a traditional bank may be preferable for people who want a wider range of financial services in one institution.
I would also skip it if I had no practical reason to use the Wisely environment. A finance app should earn its place in your routine. If your pay already arrives elsewhere and you are satisfied with your current bank’s tools, adding another app may create more checking rather than less.
My final view after weighing the trade-offs
My verdict is positive, with a clear condition: myWisely is best understood as a focused pay-and-spending companion, not an all-purpose financial command center. Its strongest quality is the way it encourages a repeatable routine around receiving money, watching purchases, and saving intentionally. That is enough to make it genuinely useful for the right audience.
I appreciate that it keeps the everyday questions in view instead of burying them under financial jargon. I also value the practical habits it can support: checking after payday, reviewing activity before the next cycle, and protecting necessary money before saving or spending freely. Those are small actions, but they are more valuable than an impressive dashboard that nobody opens.
The limitations are equally clear. Users with complex finances may outgrow its focused approach, and anyone outside its natural pay ecosystem may find little reason to switch. The app cannot decide what is safe to spend, create a complete plan for irregular income, or replace personal judgment. That is not a failure, but it should shape expectations from the start.
With a 4.3 average and more than 5 million installs, it is clearly established enough to merit consideration, while its Everyone rating makes it approachable for a broad audience. Still, my recommendation is based less on those figures than on fit. If you want a free, mobile-first way to keep pay, spending, and saving close together, I would recommend giving it a try. If you need deep financial analysis or a full banking replacement, I would pair it with another tool or choose a broader alternative instead.
In short, I would recommend it to a friend who wants more control over everyday money without turning budgeting into a second job. Used as a regular checkpoint rather than a magic solution, it offers a clear and practical path from getting paid to making more considered spending and saving decisions.
myWisely: Mobile Banking FAQ
What is myWisely: Mobile Banking used for?
myWisely: Mobile Banking is designed for Wisely cardholders who want to manage their prepaid or payroll card from a phone. After signing in, you can generally review your available balance, monitor transactions, receive account alerts, locate helpful card information, and manage selected card settings. The exact tools available may depend on your Wisely program, employer, card type, and account eligibility.
Is myWisely: Mobile Banking free to download and use?
The app is typically available to download at no charge from the official Android or iOS app store, but downloading the application does not mean every related service is free. Certain card activities, ATM withdrawals, transfers, expedited services, or other transactions may involve fees according to your Wisely account terms. Review the fee schedule shown for your card before using a specific feature.
How do I sign in to myWisely if I am a new or existing cardholder?
To use myWisely, you normally need an eligible Wisely card and the account credentials created during registration. New users may be asked to enter card or personal verification details, create login information, and confirm their identity. Existing users can sign in with their registered credentials. If you forget them or fail verification, use the in-app recovery options or contact official Wisely support.
Can I use myWisely to check transactions, deposits, and available balance?
Yes, checking account activity is one of the app’s main purposes. Depending on your card program, myWisely can show your current available balance, recent purchases, deposits, withdrawals, and other posted activity. Keep in mind that balances and transactions may not update instantly, and pending card payments can temporarily affect the amount you can spend.
Is myWisely: Mobile Banking safe for managing my card?
The application is intended to provide secure access to Wisely account services and may use sign-in protection, identity verification, alerts, and other security controls. However, your own habits remain important. Download it only from an official app store, keep your device and app updated, avoid sharing passwords or verification codes, and contact Wisely promptly if you notice an unfamiliar transaction or suspect that your card details are compromised.













